Boy was I wrong. My last post 10/10 the S&P closed at 1186, I expected an oversold bounce, instead we got further selling and didn't bounce until Friday. Here we are at 1186. I was right in pointing out that oil remains the wild card and heavily influences the movement of everything else. Today, another storm and accompaning oil price concerns. Stocks are down, dollar stronger. Oil, however is no longer a one way street. Signs of slower global growth and high prices has raised concerns of what they now call demand destruction. So we will now have tug of war. Economic data showing weakness will exert downward bias while supply disruption news will be positive. Let's not forget the weather which of course can go either way but will have more impact if it's colder than normal.
As I write, we are having an up day thanks to GM and MO which are up on GM's agreement with the UAW re health care costs, and MO's favorable ruling from the Supreme Court on tobacco litigation. Even so, I feel the bears have the upper hand in the intermediate term. As I've outlined before, the things we know augur badly for the market. The Fed will continue to tighten. Inflation continues to march higher as the higher energy prices grind their way through the economy. The budget deficits will continue to grow larger, not only because of the large expenditures lately due to hurricane relief, but now we have to worry that receipts may be lower due to a slowdown, a double whammy. Gas prices will stay high and be a drag on consumer confidence. We just don't have the refining capacity to bring them down. Outside of energy, earning are being squezzed by higher costs. It seems like everyone is blaming higher energy for earnings misses, even some that seem to have no connection. If there is a year-end rally I think we would have to see much lower oil prices for some reason and a friendlier Fed as a catalyst.
I haven't written much about the dollar lately, but we are now at an interesting juncture. The dollar has gained strength this year on higher interest rates. So far it has tested its July highs against the Euro twice at around 119 and held. Today I saw comments from both the ECB and the Bundesbank about higher interest rates down the road. Higher energy is causing inflation targets to be exceeded there also.This would of course be very supportive of the Euro, however, they have the same problem we do. Their think tanks last week lowered economic growth estimates. So the question will be, which economy slows sooner and farther and which central bank blinks first. We will trade back and forth on each data point pro or con. As the Euro is near one year lows and the U.S. capital markets are having problems, the best risk reward trade here is to go long the Euro, at least until support is broken. I like trades where the market doesn't have to move too far to let me know I'm wrong.
Monday, October 17, 2005


Monday, October 10, 2005
BOUNCE
The market was oversold. The payroll data was better then expected. Oil prices were dropping. Rally, rally, rally. The bullish argument to take away from the payroll numbers, where the previous two months were revised significantly higher, is that going into the hurricanes the economy was strong, strong , strong. With hurricane season almost over, and reconstruction money pouring into the gulf, it may have all been just a bump in the road with sunny skies ahead. Only a hawkish Fed and higher inflation are restraining prices.
Bears point out, you don't fight the Fed, much higher heating bills lie ahead, and Mutual Fund cash levels are at record lows.
I believe we are now going to test the upside. How far will this rally carry and with what kind of volume. 1210 seems like the first line of resistance in the S&P. Energy is still the wild card and the market will remain sensitive to it. This week we will have higher inflation readings and retail sales, continuing the worry over interest rates. Cold weather or large drawdowns of distillate inventories this week could halt the slide in energy.
Bears point out, you don't fight the Fed, much higher heating bills lie ahead, and Mutual Fund cash levels are at record lows.
I believe we are now going to test the upside. How far will this rally carry and with what kind of volume. 1210 seems like the first line of resistance in the S&P. Energy is still the wild card and the market will remain sensitive to it. This week we will have higher inflation readings and retail sales, continuing the worry over interest rates. Cold weather or large drawdowns of distillate inventories this week could halt the slide in energy.
Tuesday, October 04, 2005
WHAT NOW?
Yesterday the S&P finished down by 2 pts, the first down day in eight trading sessions.
True nothing much has happened in most of the last eight trading sessions, with the exception of the month-end window dressing rally. The bulls are looking for a year-end rally. Their argument is:
True nothing much has happened in most of the last eight trading sessions, with the exception of the month-end window dressing rally. The bulls are looking for a year-end rally. Their argument is:
- The uptrend from the 03 low is intact.
- The market has absorbed all the bad news and remained resilient.
- Fiscal policy will support the economy and generate corporate profitability on Katrina spending. Yesterday's ISM index, certainly supports this.
- The Fed is almost done.
- We've seen the worst on oil prices.
- The higher oil prices of the past year are working their way through consumer and corporate pocketbooks and will hurt spending and profits for the rest of the year.
- The Fed will continue tightening until they get mortgage rates up and slow housing. Greenspan is now concerned about inflating asset prices.
- Corporate profits while good, are slowing and are on a downward path. Earnings misses will be blamed on energy and Katrina.
- Inflation is in the pipeline.
- Energy prices will stay high particularly natural gas. This will significantly slow consumer spending which accounts for 70% of GDP. Evidence of stress is starting to show up in the higher percentage of consumers who are charging their gas purchases rather than paying cash. Also the percentage of consumers who are late on their credit cards has been increasing.
Friday, September 23, 2005
HALF FULL HALF EMPTY
Well, it's been crazy. Good news is bad news, bad news is good news. Many counter-intuitive moves in the market. In times like these I find it;s best to step back, reassess and try to find some anchors. For only with strong conviction can you ride out the short term swings. Some anchors or truths are:
The question is, do current prices reflect optimism or have they priced in the worst? One thing seems obvious, the market likes deficit spending. The increased fiscal spending, means and economic boost now, while payback is down the road. The budget deficit is going to be huge, but the market will worry about that later. Both politicians and corporate America live in a current quarter mentality. Nothing gets done without a crises, and planning does not look far ahead. Whatever happened to the Social Security crises.
The dollar has been strengthening lately. A German political crises has helped. The increased fiscal spending, which I have read could amount to 1 1/2% of GDP has provided even more support. With no fiscal discipline, the Fed has to continue tightening. As I've said many time before though, any economic weakness will quickly spill over to the buck. We could see the economy weakening despite the fiscal laggress because of the housing bubble bursting, the consumer being tapped out, higher rates, loss of confidence by foreigners in our financial markets.
The bonds will be important to watch over the next few months. Before this all started, we were already borrowing 80% of the worlds savings. Should their supply or preferences change where will the money come from? Even if we print it long rates will rise. Like the 70's we could have weak growth and higher inflation ahead.
- Gas prices are going to stay high. Even if Rita does minimal damage, we have enough production closed to keep things tight for some time.
- Budget deficits are going to grow significantly.
- Corporate earnings are being impacted by higher energy prices. AA today is only the latest.
- Inflation is in the pipeline
- Fed tightening will continue.
The question is, do current prices reflect optimism or have they priced in the worst? One thing seems obvious, the market likes deficit spending. The increased fiscal spending, means and economic boost now, while payback is down the road. The budget deficit is going to be huge, but the market will worry about that later. Both politicians and corporate America live in a current quarter mentality. Nothing gets done without a crises, and planning does not look far ahead. Whatever happened to the Social Security crises.
The dollar has been strengthening lately. A German political crises has helped. The increased fiscal spending, which I have read could amount to 1 1/2% of GDP has provided even more support. With no fiscal discipline, the Fed has to continue tightening. As I've said many time before though, any economic weakness will quickly spill over to the buck. We could see the economy weakening despite the fiscal laggress because of the housing bubble bursting, the consumer being tapped out, higher rates, loss of confidence by foreigners in our financial markets.
The bonds will be important to watch over the next few months. Before this all started, we were already borrowing 80% of the worlds savings. Should their supply or preferences change where will the money come from? Even if we print it long rates will rise. Like the 70's we could have weak growth and higher inflation ahead.
Thursday, September 15, 2005
DOUBLE TOP?


The market has started to give back some gains it made, if you recall, first on Katrina not expected to be as bad as feared and then when it was actually worse, on the bump from rebuilding. The 40 pt rally in S&P is a perfect example of the old sayings, that the market can do anything, the market can stay irrational longer than you can stay solvent, the market cannot be predicted using rational means, etc. The rally looks like it was a bull trap, short and powerful. No volume on the downside yet, so they all got em. The market is supported by fiscal spending on Katrina, lower oil, and hope the Fed is done or close to it.
The bonds are coming under pressure. Last week's manufacturing surveys showed very large increases in the inflation indexes. We have also had many companies start to raise prices as their energy costs increase. Oil prices are starting to pass through. If the Fed blinks they may be seen as falling behind the inflation curve. That of course would be very negative for bonds and the dollar as well.
The dollar keeps getting bailed out. First there was the failure of the referendum on the European constitution and now the deadlocked German elections. The talk is, we won't know the election results for weeks. Eventually it will recede from the headlines and since nothing has dramatically changed the dollar will resume its underlying downward move. It's a choice between the lesser of two evils.
Gold is reflecting slower growth, higher inflation, increased demand from China and India, and lower production. Back to the 70's.
Wednesday, September 07, 2005
OOOPS
You can see from the action of the bonds and the dollar today that the idea of the Fed blinking and not raising rates has reversed. Chicago Fed Pres helped that idea along with his midday comments where he voiced more concern over inflation. So it seems Greenspan will continue his mission to take away the punchbowl. I guess he wants to go out with his reputation as an inflation fighter intact. If they go ahead and raise rates, I think it will be the last time this year. Even the Treasury Secretary this morning acknowledged that the economy would slow. The political outcry that is already beginning will overwhelm the Fed's desire to raise rates if the economy fades.
A lot more news of higher spending today and higher costs. Higher transport costs from using alternate ports and methods of transportation and higher spending on everything from unemployment benefits surge to various relief expenditures. Not to mention lower tax revenues due to less people working and slowing economic activity.
A lot more news of higher spending today and higher costs. Higher transport costs from using alternate ports and methods of transportation and higher spending on everything from unemployment benefits surge to various relief expenditures. Not to mention lower tax revenues due to less people working and slowing economic activity.
THREE QUICK THOUGHTS
- Yesterday was a low volume rally, only 1.42 B shares. Today's volume doesn't seem much better. Breadth was good.
- We are seeing a divergence between the S&P and the transports. Obviously this can go on for a while. It is not a timing tool but like volume it tells you something about the character of the advance.
- McDonalds is up over a dollar on a broker upgrade. I wrote about this stock a while back when it was under the influence of rumors on it spinning off its real estate. I thought that was highly unlikely and the stock started to come back down until it came under rumors about a spinoff of its Chipolte unit. While I think that is more likely, spinning off 435 restaurants out of 30,000 is not that big a deal. European sales are improving, but total sales have been slowing on a quarterly basis since the 1st qtr of 04.
- 1st 04 - 17.8%
- 2nd04 - 11.7%
- 3rd04 - 9.8%
- 4th04 - 10.3%
- 1st05 - 7.97%
- 2nd05 - 6.3%
- Doesn't look like the receipe for a 20% gainer since 7/7.
Tuesday, September 06, 2005
Maybe we should have a natural disaster more often. Stocks are higher now than a week before we ever heard of Katrina. The U.S. govt spending machine is revving up and that is what the market likes. We're going to spend another 100 billion we don't have and that means a pretty hefty boost to GDP in the short term. Destruction of wealth does not show up in GDP but replacing that destruction does. With Europe sending us some of their product reserves of oil over the next 30 days, that should keep oil prices relatively quiescent. Inventory numbers will be released Thursday and will probably show big draws so we will be able to see the price response then. Everyone is always eager to shout the good news, the bad news will dribble out.
Energy supplies will remain tight. We will remain short of refining capacity for some time to come. Oil is still $3 bucks a gallon and along with high natural gas prices will grind away at the consumer and the economy. Most of the government spending is going to security, housing, clean-up, repair etc. Relief spending does not increase productive capacity or profitability, regardless of how necessary it is.
Energy supplies will remain tight. We will remain short of refining capacity for some time to come. Oil is still $3 bucks a gallon and along with high natural gas prices will grind away at the consumer and the economy. Most of the government spending is going to security, housing, clean-up, repair etc. Relief spending does not increase productive capacity or profitability, regardless of how necessary it is.
BACK TO WORK
It looks like we will start post Labor Day trading with a bounce. The market seems to be taking heart from lower oil and gas prices as a result of crude coming out of the SPR and products coming from IEA reserves. Also progress is finally being made in Louisiana. So the glass is half full at the moment.
The volatility in perception will continue for the next several months at least. The data will be lousy, but if you wish to view the glass as half full you can ignore it as temporary, due to Katrina. The bears will view it more ominoulsy of course, as undermining the fabric of economic growth. I continue to lean toward the bears and view this shock as one pushing and economy that was already slowing toward stall speed and a recession next year.
The volatility in perception will continue for the next several months at least. The data will be lousy, but if you wish to view the glass as half full you can ignore it as temporary, due to Katrina. The bears will view it more ominoulsy of course, as undermining the fabric of economic growth. I continue to lean toward the bears and view this shock as one pushing and economy that was already slowing toward stall speed and a recession next year.
Wednesday, August 31, 2005
THE DOLLAR- WATCH OUT BELOW
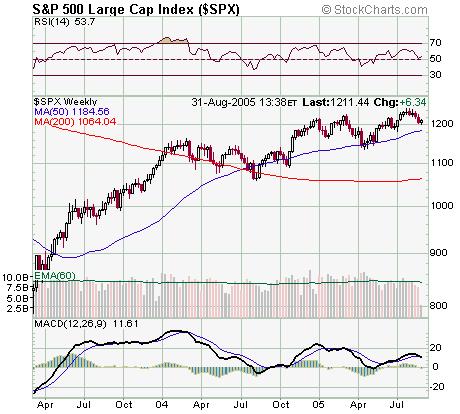
On Aug 19, I said "We have had our first small whiff of possible economic slowdown and the buck was non-plussed. When the market gets stronger evidence of this possibility and starts to look forward to the day the Fed blinks, put a fork in it, the dollar rally is done.". Well, I think we are there. The fallout from hurricane Katrina will slow the economy. This will reduce the growth differential between us and Europe and stop the interest rate difference from widening further. Yes this will slow global growth but Europe will be seen as being less leveraged than the U.S. and of course they are not pursuing a Mideast war that is going badly. Can you imagine what our trade deficit is going to look like.
A weakening dollar and high oil prices should also be bullish for gold. I worry about gold stocks though, because they use so much energy in their operations and the gold price has not gone anywhere since year-end while oil is up 65%. Their margins are getting crushed.
The S&P topped out at 1246. If it could have made it to 1253, that would have been a .618 retracement from the 3/24/00 high of 1553 and the 10/10/02 of 768. Close enough for me . Take a look at a weekly chart and you can see this may have just begun.
Finally, the law of unintended consequences is at work. The ramifications of the hurricane and our responses have just barely been scratched. This will be a story with staying power.
Their will be negative news flow from these consequences for some time.
Friday, August 26, 2005
LIQUIDITY
Throw out yesterday because the range was so narrow and stocks have finished near the lows of the day for 7 days running. I wonder when the last time that occurred? Ever since Walmart said gas is affecting sales 8/16, we have been in a funk. The homebuilders, retailers and banks are taking the brunt. We have rolled over. How far and how fast do we go. Think about this. Short term CD rates, 6mth, are almost 4%. That's beat a lot of asset classes lately, RISK FREE! I mean stocks, gold, bonds, etc have been mostly sideways. With all the uncertainty over oil prices effect on asset values and all bubble talk over real estate, these kind of short rates are going to start draining liquidity out of risk assets. In three weeks the Feds going to give you another 1/4%.
The CEO of DRD gold commented that the oil/gold ratio was at historical lows and had a long way to go up to catch up. That can be said just about everything. The price of oil is outstripping everything, and either prices rise or profits fall, particularly amongst heavy energy users like airlines, mining and chemicals to name a few. It doesn't look like prices are rising.
The CEO of DRD gold commented that the oil/gold ratio was at historical lows and had a long way to go up to catch up. That can be said just about everything. The price of oil is outstripping everything, and either prices rise or profits fall, particularly amongst heavy energy users like airlines, mining and chemicals to name a few. It doesn't look like prices are rising.
Thursday, August 25, 2005
AUGUST 25, 2005

The bond market has retraced about 1/2 of it's losses from July highs to August lows. This is where the rubber meets the road. The yield curve shouldn't flatten any further especially after hawkish statements by the Chicago Fed Prez yesterday, unless the economy is really rolling over, which may well be the case. But one would think that we would really have a battle here for days if not weeks.
Pre opening it looks like stocks could get a bounce today. They are oversold. The hurricane looks like it will miss oil installations so crude is of its highs. But if your going to play the rallies in this type of environment, remember they are most likely going to be sharp and short.
You can almost feel the consensus build on CNBC one by one that oil is finally going to hurt the economy and markets. I might go one further and say its baked in the cake. Past price increases are now working their way through the economy and profit chains and we will see negative news flow continue to grind away. Local news yesterday reporting on the impact on local governments that operate huge fleets of school buses bracing for huge budget shortfalls as a consequence of higher gas. Isn't school just about to start
It is amazing how quickly the perspective on oil has changed. It was only 2yrs ago that oil was trading at $30 a barrel midway between its decade range of $20-40. That's when OPEC was concerned about losing market share, limiting production output, afraid of high prices causing a drop in demand, concern over alternative fuels etc. Today an analyst on CNBC is concerned over Venezuela or Iran withholding a measly hundred thousand barrels of oil for political purposes. To punish the U.S. and display their power, which they could easily do as they are awash in oil riches. It almost seems like any place that produces the stuff has potential geo political issues so that we will never return to the placid world we knew before. As I've said before price will ration supply
Wednesday, August 24, 2005
AUGUST 24, 2005
Is it me or does the market feel really really heavy. About week ago I wrote about the correlation between strong stock closings with strong bond closings with oil having little influence. The past 5 trading sessions has seen a complete reversal of that correlation. For the past 4 trading sessions bonds have closed near the highs of their daily range while stocks near the low of their daily range. More importantly, every trading session since Walmart reported earnings 8/16 and said they were concerned about gas prices hurting sales, stocks have closed at low end of the trading range for the day. Bonds started their rally shortly thereafter
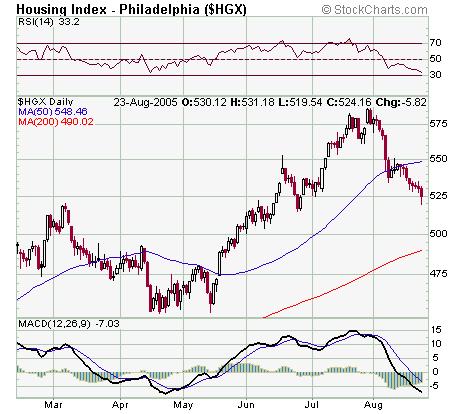
 . Data showing the housing boom may be slowing hurt the homebuilders that even the bond rally couldn't help. To ice the cake, a couple days after the Walmart news, oil after trading as low as $62.25 started moving back up dashing hopes of an intermediate correction.
So here we sit. Our leadership of retail and homebuilders has rolled over, oil is close to threatening the highs again. Google the poster child of the bulls, may be rolling over. It will be interesting to see if their news today about introducing instant messaging lifts the shares back over $300 the next few days. Anecdotal stories about higher gas prices inflicting pain are now every where and multiplying. Airlines are getting killed, farmers are getting hurt, delivery companies, big energy users off all types and stripes. It's becoming the lead story on the evening news and that can't be good for confidence. The worst month for the market is around the corner and the big boys will be back from vacation soon.

 . Data showing the housing boom may be slowing hurt the homebuilders that even the bond rally couldn't help. To ice the cake, a couple days after the Walmart news, oil after trading as low as $62.25 started moving back up dashing hopes of an intermediate correction.
So here we sit. Our leadership of retail and homebuilders has rolled over, oil is close to threatening the highs again. Google the poster child of the bulls, may be rolling over. It will be interesting to see if their news today about introducing instant messaging lifts the shares back over $300 the next few days. Anecdotal stories about higher gas prices inflicting pain are now every where and multiplying. Airlines are getting killed, farmers are getting hurt, delivery companies, big energy users off all types and stripes. It's becoming the lead story on the evening news and that can't be good for confidence. The worst month for the market is around the corner and the big boys will be back from vacation soon.
Friday, August 19, 2005
AUGUST 19, 2005
Yesterday's low in oil $62.25 was 8/1 high. So we are basically unch in oil for the month. Bond yields on the other hand, after falling most of the month have rallied over the past few days and are lower around the 4.20 level from 4.30 at the start of the month. So why is the S&P 20 pts lower. The DOW by the way has fared better, as a series of individual stories helped propel individual stocks. We had the MCD rumors of a real estate play. MO got a favorable court ruling, HPQ reported good earnings and popped $3 bucks. I think higher gas prices and WMT's warning have spooked the market. No knockout blow has been delivered by either bull or bear, but we are starting to tilt lower.
The bond rallied as oil prices hit $67 indicating the vigilantes do not see inflation and are more concerned about a consequent economic slowdown. Each major bond rally has been accompanied by a spike in refi's that kept the economy going. But each refi spike has been smaller than the last. The psychological effect of these gas prices may curtail refis even more this time, even if the bonds continue their economic weakness rally in the face of Fed tightening. The consumer may flinch about borrowing more. Then we will have arrived at the proverbial pushing on a string.
The dollar has had a nice rally this week on the back of data showing greater inflow of funds into Treasuries from abroad and the outlook for further Fed tightening continuing to add to our yield advantage. We have had our first small whiff of possible economic slowdown and the buck was non plussed. When the market gets stronger evidence of this possibility and starts to look forward to the day the Fed blinks, put a fork in it the dollar rally is done.
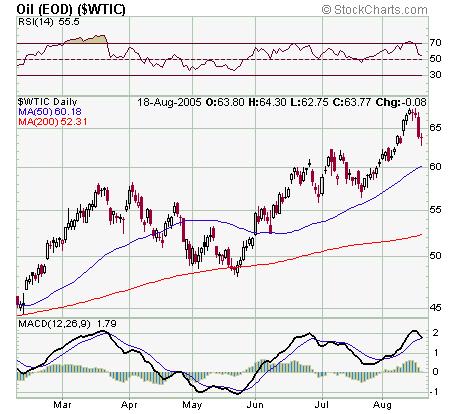
The bond rallied as oil prices hit $67 indicating the vigilantes do not see inflation and are more concerned about a consequent economic slowdown. Each major bond rally has been accompanied by a spike in refi's that kept the economy going. But each refi spike has been smaller than the last. The psychological effect of these gas prices may curtail refis even more this time, even if the bonds continue their economic weakness rally in the face of Fed tightening. The consumer may flinch about borrowing more. Then we will have arrived at the proverbial pushing on a string.
The dollar has had a nice rally this week on the back of data showing greater inflow of funds into Treasuries from abroad and the outlook for further Fed tightening continuing to add to our yield advantage. We have had our first small whiff of possible economic slowdown and the buck was non plussed. When the market gets stronger evidence of this possibility and starts to look forward to the day the Fed blinks, put a fork in it the dollar rally is done.
Monday, August 15, 2005
AUGUST 15, 2005
An interesting correlation last week, well actually since 8/2, is that every day the bond market closed near the high of its range for the day, so did stocks, regardless of what oil prices did. The opposite was true as well. Every day bonds closed near their lows of the range of the day, so did stocks, even if oil fell like it did 8/4. So oil didn't matter or its rise was compensated for by lower interest rates. Friday, however stocks closed neutral, about the middle of their range for the day, even though bonds had a big rally and finished strong. Oil might finally be exerting some influence as it broke the $67 barrier with fears of $70 around the corner. Inflation measures this week and gas pump prices will be negative, as will lingering concerns over tech stocks in light of DELL and CISCO. Earnings from retailers should be good, but it will be their guidance that matters most.
I don't usually comment a lot on individual stocks but the action in McDonald's last week, is to good to pass up. Rumors of a big REIT like Vornado buying a stake in the company to monetize it's real estate values sent the stock and its call options flying last week. MCD started to hit its lows in the spring of 2003, as same store sales were declining 4% a month. MCD had been a growth stock for decades and old management in an effort to keep that up started to diversify into other restaurant concepts in the late 90's as expansion opportunities waned and competition increased for their burger joints. That strategy failed, as their forays into other businesses never reached critical mass to contribute significantly to the bottom line and meanwhile tastes were changing as the population aged and they had their eye off the ball of their core business and it faltered. New management was brought in, cutoff all the expansion focused on the core business, introducing new menu items to cater to older and healthier tastes, extended store hours etc. Essentially pushing more product through existing distribution. It worked. Same store sales started to improve peaking at 13.9% growth in the spring of 2004. So from its low of around $14 a share in 2/03 the stock rallied to 34 1/2 in 3/05. But then same store sales started to settle down, as the comparisons grew more difficult and the stock pulled back to 27. June and July were better than April and May and so the stock bounced back a little to 31. The company itself is looking for mid single digit EPS growth. They fixed the business but are now in the same spot the old management was. How do you get growth out of a large, mature business going forward. They're already the biggest in every thing. They have the largest breakfast business, they expanded their menu, expanded their hours to get the late night crowd. By slowing international and domestic expansion and eschewing other restaurant concepts, they are back to being a one trick pony. Grow same store sales. This can be seen in the convergence of same store sales figures and total sales figures.
That brings us to the present. Up pops the rumor of Vornado, perhaps helped by the fact that they just recently raised some money in a secondary offering. Roughly 9m share at their current price, lets say 90 equals about 800M, sounds like a lot. Could it pop the stock $4? Sure, but consider this. MCD bought back 33M of its share in the last 6 months, approximately 1 billion dollars without much effect. Not to mention several analysts pointed out on Friday that MCD is not like Kmart. Though they have some nice parcels, most McDonald's are located on major streets next to gas stations and dry cleaners and the parcels are not that large if you are considering re-development. McDonald's picks their sites for a reason, so I don't think they want to go anywhere in the first place. Do they need the cash, that spinning them off in a REIT might provide. They have no major expansion plans, just the opposite.
Maybe someone should look into who benefited most from these rumors.
I don't usually comment a lot on individual stocks but the action in McDonald's last week, is to good to pass up. Rumors of a big REIT like Vornado buying a stake in the company to monetize it's real estate values sent the stock and its call options flying last week. MCD started to hit its lows in the spring of 2003, as same store sales were declining 4% a month. MCD had been a growth stock for decades and old management in an effort to keep that up started to diversify into other restaurant concepts in the late 90's as expansion opportunities waned and competition increased for their burger joints. That strategy failed, as their forays into other businesses never reached critical mass to contribute significantly to the bottom line and meanwhile tastes were changing as the population aged and they had their eye off the ball of their core business and it faltered. New management was brought in, cutoff all the expansion focused on the core business, introducing new menu items to cater to older and healthier tastes, extended store hours etc. Essentially pushing more product through existing distribution. It worked. Same store sales started to improve peaking at 13.9% growth in the spring of 2004. So from its low of around $14 a share in 2/03 the stock rallied to 34 1/2 in 3/05. But then same store sales started to settle down, as the comparisons grew more difficult and the stock pulled back to 27. June and July were better than April and May and so the stock bounced back a little to 31. The company itself is looking for mid single digit EPS growth. They fixed the business but are now in the same spot the old management was. How do you get growth out of a large, mature business going forward. They're already the biggest in every thing. They have the largest breakfast business, they expanded their menu, expanded their hours to get the late night crowd. By slowing international and domestic expansion and eschewing other restaurant concepts, they are back to being a one trick pony. Grow same store sales. This can be seen in the convergence of same store sales figures and total sales figures.
That brings us to the present. Up pops the rumor of Vornado, perhaps helped by the fact that they just recently raised some money in a secondary offering. Roughly 9m share at their current price, lets say 90 equals about 800M, sounds like a lot. Could it pop the stock $4? Sure, but consider this. MCD bought back 33M of its share in the last 6 months, approximately 1 billion dollars without much effect. Not to mention several analysts pointed out on Friday that MCD is not like Kmart. Though they have some nice parcels, most McDonald's are located on major streets next to gas stations and dry cleaners and the parcels are not that large if you are considering re-development. McDonald's picks their sites for a reason, so I don't think they want to go anywhere in the first place. Do they need the cash, that spinning them off in a REIT might provide. They have no major expansion plans, just the opposite.
Maybe someone should look into who benefited most from these rumors.
Thursday, August 11, 2005
AUGUST 11, 2005
Since 6/27 the S&P has gone from 1190 to 1230, oil from 60 to 65 bond yields from 4% to 4.40% and fed funds from 3.25% to 3.5%. We might have hit a tipping point today. The reason I say this is that rising bond yields are finally starting to raise mortgage rates. Both the homebuilders and banks have rolled over. Oil at 65 will put pump prices at new records and finally influence consumer behavior. Gas prices always came back down in the past. New records will put that into question in consumer minds. 1253 is strong resistance and I thought we would challenge it at least once. We still might if something caused a selloff in oil, but stop waiting for inventories to do it. In commodities, price leads inventories. To me, oil looks like its entering the final phase of a blowoff top. I would not venture a guess to where that top could be. Bull markets in commodities accelerate near the end of their movcs. Remember gold going to 850? It was moving $50 a day toward the end, or beans in the teens or nasdaq to 5000, you get the idea. Pick a top? Not me. It's just doing its job. With so much demand, price has to ration supply. The danger of course is that we can't seem to do anything about it and the price might break the economy. I know the Fed will ease, but this time it may finally be pushing on a string.
The market acts like it definitely wants to go up. Any slight pullback in oil is an excuse for a rally. Rising bond yeilds however, seem to stop it in its tracks. Something to be on the alert for is any sign of economic weakness might cause a bond rally which ironically might ignite stocks. Short banks, homebuilders, and retail and stay long the energy group.
Even though the interest rate spread continues to widen in the dollar's favor, it continues to weaken. Stronger economic fundamentals in Euroland and Japan are overriding the rate advantage. Gold and gold shares have gone along for the ride. Higher oil and commodities in general are also pulling gold along. If bond yeilds continue to rise, can this continue? Opinions welcome.
The market acts like it definitely wants to go up. Any slight pullback in oil is an excuse for a rally. Rising bond yeilds however, seem to stop it in its tracks. Something to be on the alert for is any sign of economic weakness might cause a bond rally which ironically might ignite stocks. Short banks, homebuilders, and retail and stay long the energy group.
Even though the interest rate spread continues to widen in the dollar's favor, it continues to weaken. Stronger economic fundamentals in Euroland and Japan are overriding the rate advantage. Gold and gold shares have gone along for the ride. Higher oil and commodities in general are also pulling gold along. If bond yeilds continue to rise, can this continue? Opinions welcome.
Monday, August 08, 2005
AUGUST 8, 2005
Stocks did creep higher as I suggested in my last post, until they ran into weaker retail sales and higher oil. Bonds continue to be short and although the dollar did not get to 118 euro, I was correct in thinking it was about time to short the dollar.
Oil stocks have been the undisputed leaders, followed by homebuilders and retailers. So it should be. We are after all a consumption based economy. Financial stocks are the biggest sector of the S&P, and they have lagged badly. The higher bond yields and oil prices hurt 3 out of the four sectors very badly. Homebuilders look like they have finally topped out helped along by prodigious selling by insiders of course. The flat yield curve is hurting net interest margins and so the banks stocks got hit. The BKX looks like its broken down. Retailer's also were sold, starting with Target, the subject of a bearish Barrons article. The group sports pretty high PEs for such large companies in such a mundane businesses. Over the long run their sales growth can't run ahead of GDP. Just ask WMT. That leaves the energy stocks, and at least today they can't lift the entire market by themselves.
A few recent indicators have also become troubling. Sentiment, as reflected in the number of weeks that bulls have outnumbered bears at 145 is approaching its record of 152 weeks. Mutual Fund cash levels are at historic lows. Real Estate as a percentage of GDP is at a historic high. Insider selling is very high. The breadth divergence between big and small stocks is very wide. The current acct deficit at 6 1/2% of GDP is in no mans land. None of these are very good timing indicators, but together they do paint a picture of caution. We can't all get out the door at the same time.
Oil stocks have been the undisputed leaders, followed by homebuilders and retailers. So it should be. We are after all a consumption based economy. Financial stocks are the biggest sector of the S&P, and they have lagged badly. The higher bond yields and oil prices hurt 3 out of the four sectors very badly. Homebuilders look like they have finally topped out helped along by prodigious selling by insiders of course. The flat yield curve is hurting net interest margins and so the banks stocks got hit. The BKX looks like its broken down. Retailer's also were sold, starting with Target, the subject of a bearish Barrons article. The group sports pretty high PEs for such large companies in such a mundane businesses. Over the long run their sales growth can't run ahead of GDP. Just ask WMT. That leaves the energy stocks, and at least today they can't lift the entire market by themselves.
A few recent indicators have also become troubling. Sentiment, as reflected in the number of weeks that bulls have outnumbered bears at 145 is approaching its record of 152 weeks. Mutual Fund cash levels are at historic lows. Real Estate as a percentage of GDP is at a historic high. Insider selling is very high. The breadth divergence between big and small stocks is very wide. The current acct deficit at 6 1/2% of GDP is in no mans land. None of these are very good timing indicators, but together they do paint a picture of caution. We can't all get out the door at the same time.
Wednesday, July 27, 2005
JULY 26, 2005
The market continues firm since my last post. The S&P is up about 9 points to 1233. Bonds and the dollar have not changed one iota. Let's be honest. We are in the summer doldrums. We have had a China revaluation, lots and lots of earnings, Greenspan testimony, and the usual economic stats, and nothing is moving the markets very much. Volatility is so low its hard to sit through a whole day of trading. What are you e-mini traders doing?
It would not surprise me to see stocks continue to creep higher. I'll try another short at 1250 on the S&P. I'll stay short bonds untill I see economic weakness and I will start thinking about a short dollar position if the euro falls to the 117-118 area.
There is a lot of talk lately that oil has reached a short to intermediate top. This will be important if true. Energy stocks have been the leaders that have pulled the market higher. Financial stocks have lagged. Some of the big banks in their earning reports had lower net intest income because of the flat yield curve. The other leaders in the market and the economy , are the homebuilders and retail stocks. They have had great runs and are near their highs, but look tired. If oil comes down, what's going to pull the market higher.
It would not surprise me to see stocks continue to creep higher. I'll try another short at 1250 on the S&P. I'll stay short bonds untill I see economic weakness and I will start thinking about a short dollar position if the euro falls to the 117-118 area.
There is a lot of talk lately that oil has reached a short to intermediate top. This will be important if true. Energy stocks have been the leaders that have pulled the market higher. Financial stocks have lagged. Some of the big banks in their earning reports had lower net intest income because of the flat yield curve. The other leaders in the market and the economy , are the homebuilders and retail stocks. They have had great runs and are near their highs, but look tired. If oil comes down, what's going to pull the market higher.
Monday, July 18, 2005
JULY 18, 2005
The S&P is up 28 pts from my last post, from 1196 to 1224. The prime mover in my mind being that so far there has been no visible impact on the economy or earnings from either higher oil or higher short term interest rates. Those of us, and we are legion, who thought the consumer was overleveraged, underpaid, undersaved, and would be hurt by low income growth in wages and salaries, and squeezed by higher oil prices and rates, Not!!!!! Neither higher gas prices or heating bills or air condidioning for that matter, which have increased substantially, look no further than the huge increase from utilitiies in the latest industrial output report, have made much of a difference lately, Look no further than the latest strong retail sales report. Think pent up demand has been spent, think sales have been pulled forward. No evidence in sight yet. Look at the appettite for SUV's during GM's latest sales incentive.
The consumer cuts back his standard of living very reluctantly, even during recessions, studies have shown. The housing bubble has let homeowners extract ever increasing amounts of cash out of their equity according to BCA Research in their July 7 report. As postulated in an earlier post, and end to this process could likely be the trigger for the inevitable economic slowdown. As has been shown in Holland and the U.K. even just a flattenting in home prices can be quickly felt in retail spending. Even super bears are starting to throw in the towel or waffle on their timing, like Michael Metz last week. There are a few signs, like the dollar stores are underperforming the retail index, and they of course cater to the lowest strata of shoppers. Fewer new home buyers can qualify for loans due to higher home prices in hot markets. Signs like these will have to become more wide spread for the market to take heed. We will be patient in the meantime.
Friday and today the market seems to have stalled. The leaders, oil stocks an homebuilders have sucumbed to profit taking. Oil inventories seem comfortable and the hurricane fears have receded, so taking some chips off the table seems reasonable. All this talk of the Fed not stopping soon provides a similar excuse in the homebuilders after some big moves. Today Citi also dissapointed, in the biggest sector of the market. Last week Fifth Third as well. The Contrarian Investor.com had a great report foreshaowding these results.
I'm still short bonds. Nothing has happened to change my mind, that until we see some economic weakness the curve will have trouble flattening further, and the Fed will push rates higher. The dollar will be supported as long as higher rates are expected.
The consumer cuts back his standard of living very reluctantly, even during recessions, studies have shown. The housing bubble has let homeowners extract ever increasing amounts of cash out of their equity according to BCA Research in their July 7 report. As postulated in an earlier post, and end to this process could likely be the trigger for the inevitable economic slowdown. As has been shown in Holland and the U.K. even just a flattenting in home prices can be quickly felt in retail spending. Even super bears are starting to throw in the towel or waffle on their timing, like Michael Metz last week. There are a few signs, like the dollar stores are underperforming the retail index, and they of course cater to the lowest strata of shoppers. Fewer new home buyers can qualify for loans due to higher home prices in hot markets. Signs like these will have to become more wide spread for the market to take heed. We will be patient in the meantime.
Friday and today the market seems to have stalled. The leaders, oil stocks an homebuilders have sucumbed to profit taking. Oil inventories seem comfortable and the hurricane fears have receded, so taking some chips off the table seems reasonable. All this talk of the Fed not stopping soon provides a similar excuse in the homebuilders after some big moves. Today Citi also dissapointed, in the biggest sector of the market. Last week Fifth Third as well. The Contrarian Investor.com had a great report foreshaowding these results.
I'm still short bonds. Nothing has happened to change my mind, that until we see some economic weakness the curve will have trouble flattening further, and the Fed will push rates higher. The dollar will be supported as long as higher rates are expected.
Friday, July 01, 2005
JULY 1, 2005
The S&P is down about 15pts from my last post, from 1211 to 1196. What has happened is that oil reached the tipping point of $60. Oil had been advancing smartly the weeks before by about 8% without any adverse impact on stocks. But a $60 oil price was enough to cause a couple of triple digit down days for the Dow. The market then got back 50% of its losses, recovering to 1204 when oil broke back below $57. There was also some hope that the Fed might signal an end to their rate increases. Those hopes were dashed yesterday and the market sold off. Economic wise, we get a nice bounce in the purchasing managers index and the consumer sentiment numbers are supportive. The economic news has not been a big mover lately.
It is all about the Fed, oil and soon earnings. The euro fell below 1.20 today, not good for multinational earnings. The Fed is not done, also not good for the market. There is no sign of economic weakness in housing and autos. If you squint you might see the consumer slowing down a little. To me it all adds up to oil and earnings being the swing factors over the next couple of weeks. I'm skeptical of this fall in oil being little more than profit taking after hitting a big round number as the oil stocks gave up very little. On profits I fear higher commodity cost and a stronger dollar hurting margins. I'm shorting the market on rallies with a stop at 1206.
I'm short term bearish on the bonds now. I think the curve will have trouble flattening further until we see some sign of economic weakness, so I've gone short for a trade. Prices have approached the old highs and they are technically overbought.
The euro looks like it can fall to 117-118. Like Bill Gross I believe economic weakness is enevitable down the road and that is what I think will turn the buck lower again. For now the interest rate theme provides the lift.
It is all about the Fed, oil and soon earnings. The euro fell below 1.20 today, not good for multinational earnings. The Fed is not done, also not good for the market. There is no sign of economic weakness in housing and autos. If you squint you might see the consumer slowing down a little. To me it all adds up to oil and earnings being the swing factors over the next couple of weeks. I'm skeptical of this fall in oil being little more than profit taking after hitting a big round number as the oil stocks gave up very little. On profits I fear higher commodity cost and a stronger dollar hurting margins. I'm shorting the market on rallies with a stop at 1206.
I'm short term bearish on the bonds now. I think the curve will have trouble flattening further until we see some sign of economic weakness, so I've gone short for a trade. Prices have approached the old highs and they are technically overbought.
The euro looks like it can fall to 117-118. Like Bill Gross I believe economic weakness is enevitable down the road and that is what I think will turn the buck lower again. For now the interest rate theme provides the lift.
Subscribe to:
Posts (Atom)