skip to main |
skip to sidebar
 On Aug 19, I said "We have had our first small whiff of possible economic slowdown and the buck was non-plussed. When the market gets stronger evidence of this possibility and starts to look forward to the day the Fed blinks, put a fork in it, the dollar rally is done.". Well, I think we are there. The fallout from hurricane Katrina will slow the economy. This will reduce the growth differential between us and Europe and stop the interest rate difference from widening further. Yes this will slow global growth but Europe will be seen as being less leveraged than the U.S. and of course they are not pursuing a Mideast war that is going badly. Can you imagine what our trade deficit is going to look like.
A weakening dollar and high oil prices should also be bullish for gold. I worry about gold stocks though, because they use so much energy in their operations and the gold price has not gone anywhere since year-end while oil is up 65%. Their margins are getting crushed.
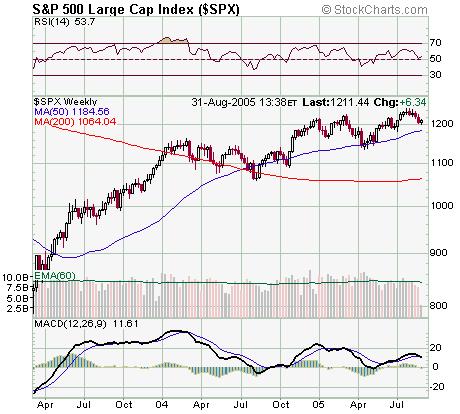
The S&P topped out at 1246. If it could have made it to 1253, that would have been a .618 retracement from the 3/24/00 high of 1553 and the 10/10/02 of 768. Close enough for me . Take a look at a weekly chart and you can see this may have just begun.
Finally, the law of unintended consequences is at work. The ramifications of the hurricane and our responses have just barely been scratched. This will be a story with staying power.
Their will be negative news flow from these consequences for some time.
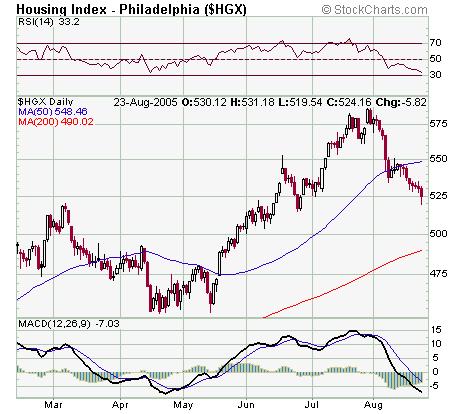
Throw out yesterday because the range was so narrow and stocks have finished near the lows of the day for 7 days running. I wonder when the last time that occurred? Ever since Walmart said gas is affecting sales 8/16, we have been in a funk. The homebuilders, retailers and banks are taking the brunt. We have rolled over. How far and how fast do we go. Think about this. Short term CD rates, 6mth, are almost 4%. That's beat a lot of asset classes lately, RISK FREE! I mean stocks, gold, bonds, etc have been mostly sideways. With all the uncertainty over oil prices effect on asset values and all bubble talk over real estate, these kind of short rates are going to start draining liquidity out of risk assets. In three weeks the Feds going to give you another 1/4%.
The CEO of DRD gold commented that the oil/gold ratio was at historical lows and had a long way to go up to catch up. That can be said just about everything. The price of oil is outstripping everything, and either prices rise or profits fall, particularly amongst heavy energy users like airlines, mining and chemicals to name a few. It doesn't look like prices are rising.
 The bond market has retraced about 1/2 of it's losses from July highs to August lows. This is where the rubber meets the road. The yield curve shouldn't flatten any further especially after hawkish statements by the Chicago Fed Prez yesterday, unless the economy is really rolling over, which may well be the case. But one would think that we would really have a battle here for days if not weeks.
Pre opening it looks like stocks could get a bounce today. They are oversold. The hurricane looks like it will miss oil installations so crude is of its highs. But if your going to play the rallies in this type of environment, remember they are most likely going to be sharp and short.
You can almost feel the consensus build on CNBC one by one that oil is finally going to hurt the economy and markets. I might go one further and say its baked in the cake. Past price increases are now working their way through the economy and profit chains and we will see negative news flow continue to grind away. Local news yesterday reporting on the impact on local governments that operate huge fleets of school buses bracing for huge budget shortfalls as a consequence of higher gas. Isn't school just about to start
It is amazing how quickly the perspective on oil has changed. It was only 2yrs ago that oil was trading at $30 a barrel midway between its decade range of $20-40. That's when OPEC was concerned about losing market share, limiting production output, afraid of high prices causing a drop in demand, concern over alternative fuels etc. Today an analyst on CNBC is concerned over Venezuela or Iran withholding a measly hundred thousand barrels of oil for political purposes. To punish the U.S. and display their power, which they could easily do as they are awash in oil riches. It almost seems like any place that produces the stuff has potential geo political issues so that we will never return to the placid world we knew before. As I've said before price will ration supply
Is it me or does the market feel really really heavy. About week ago I wrote about the correlation between strong stock closings with strong bond closings with oil having little influence. The past 5 trading sessions has seen a complete reversal of that correlation. For the past 4 trading sessions bonds have closed near the highs of their daily range while stocks near the low of their daily range. More importantly, every trading session since Walmart reported earnings 8/16 and said they were concerned about gas prices hurting sales, stocks have closed at low end of the trading range for the day. Bonds started their rally shortly thereafter
 . Data showing the housing boom may be slowing hurt the homebuilders that even the bond rally couldn't help. To ice the cake, a couple days after the Walmart news, oil after trading as low as $62.25 started moving back up dashing hopes of an intermediate correction.
So here we sit. Our leadership of retail and homebuilders has rolled over, oil is close to threatening the highs again. Google the poster child of the bulls, may be rolling over. It will be interesting to see if their news today about introducing instant messaging lifts the shares back over $300 the next few days. Anecdotal stories about higher gas prices inflicting pain are now every where and multiplying. Airlines are getting killed, farmers are getting hurt, delivery companies, big energy users off all types and stripes. It's becoming the lead story on the evening news and that can't be good for confidence. The worst month for the market is around the corner and the big boys will be back from vacation soon.
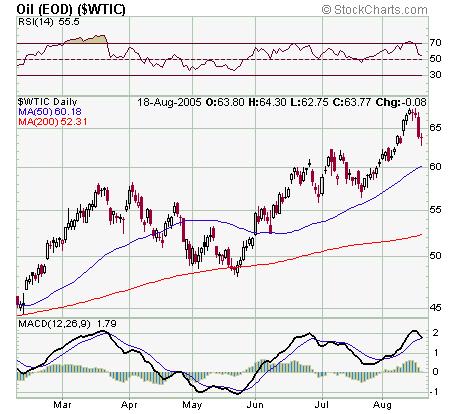
Yesterday's low in oil $62.25 was 8/1 high. So we are basically unch in oil for the month. Bond yields on the other hand, after falling most of the month have rallied over the past few days and are lower around the 4.20 level from 4.30 at the start of the month. So why is the S&P 20 pts lower. The DOW by the way has fared better, as a series of individual stories helped propel individual stocks. We had the MCD rumors of a real estate play. MO got a favorable court ruling, HPQ reported good earnings and popped $3 bucks. I think higher gas prices and WMT's warning have spooked the market. No knockout blow has been delivered by either bull or bear, but we are starting to tilt lower.
The bond rallied as oil prices hit $67 indicating the vigilantes do not see inflation and are more concerned about a consequent economic slowdown. Each major bond rally has been accompanied by a spike in refi's that kept the economy going. But each refi spike has been smaller than the last. The psychological effect of these gas prices may curtail refis even more this time, even if the bonds continue their economic weakness rally in the face of Fed tightening. The consumer may flinch about borrowing more. Then we will have arrived at the proverbial pushing on a string.
The dollar has had a nice rally this week on the back of data showing greater inflow of funds into Treasuries from abroad and the outlook for further Fed tightening continuing to add to our yield advantage. We have had our first small whiff of possible economic slowdown and the buck was non plussed. When the market gets stronger evidence of this possibility and starts to look forward to the day the Fed blinks, put a fork in it the dollar rally is done.
An interesting correlation last week, well actually since 8/2, is that every day the bond market closed near the high of its range for the day, so did stocks, regardless of what oil prices did. The opposite was true as well. Every day bonds closed near their lows of the range of the day, so did stocks, even if oil fell like it did 8/4. So oil didn't matter or its rise was compensated for by lower interest rates. Friday, however stocks closed neutral, about the middle of their range for the day, even though bonds had a big rally and finished strong. Oil might finally be exerting some influence as it broke the $67 barrier with fears of $70 around the corner. Inflation measures this week and gas pump prices will be negative, as will lingering concerns over tech stocks in light of DELL and CISCO. Earnings from retailers should be good, but it will be their guidance that matters most.
I don't usually comment a lot on individual stocks but the action in McDonald's last week, is to good to pass up. Rumors of a big REIT like Vornado buying a stake in the company to monetize it's real estate values sent the stock and its call options flying last week. MCD started to hit its lows in the spring of 2003, as same store sales were declining 4% a month. MCD had been a growth stock for decades and old management in an effort to keep that up started to diversify into other restaurant concepts in the late 90's as expansion opportunities waned and competition increased for their burger joints. That strategy failed, as their forays into other businesses never reached critical mass to contribute significantly to the bottom line and meanwhile tastes were changing as the population aged and they had their eye off the ball of their core business and it faltered. New management was brought in, cutoff all the expansion focused on the core business, introducing new menu items to cater to older and healthier tastes, extended store hours etc. Essentially pushing more product through existing distribution. It worked. Same store sales started to improve peaking at 13.9% growth in the spring of 2004. So from its low of around $14 a share in 2/03 the stock rallied to 34 1/2 in 3/05. But then same store sales started to settle down, as the comparisons grew more difficult and the stock pulled back to 27. June and July were better than April and May and so the stock bounced back a little to 31. The company itself is looking for mid single digit EPS growth. They fixed the business but are now in the same spot the old management was. How do you get growth out of a large, mature business going forward. They're already the biggest in every thing. They have the largest breakfast business, they expanded their menu, expanded their hours to get the late night crowd. By slowing international and domestic expansion and eschewing other restaurant concepts, they are back to being a one trick pony. Grow same store sales. This can be seen in the convergence of same store sales figures and total sales figures.
That brings us to the present. Up pops the rumor of Vornado, perhaps helped by the fact that they just recently raised some money in a secondary offering. Roughly 9m share at their current price, lets say 90 equals about 800M, sounds like a lot. Could it pop the stock $4? Sure, but consider this. MCD bought back 33M of its share in the last 6 months, approximately 1 billion dollars without much effect. Not to mention several analysts pointed out on Friday that MCD is not like Kmart. Though they have some nice parcels, most McDonald's are located on major streets next to gas stations and dry cleaners and the parcels are not that large if you are considering re-development. McDonald's picks their sites for a reason, so I don't think they want to go anywhere in the first place. Do they need the cash, that spinning them off in a REIT might provide. They have no major expansion plans, just the opposite.
Maybe someone should look into who benefited most from these rumors.
Since 6/27 the S&P has gone from 1190 to 1230, oil from 60 to 65 bond yields from 4% to 4.40% and fed funds from 3.25% to 3.5%. We might have hit a tipping point today. The reason I say this is that rising bond yields are finally starting to raise mortgage rates. Both the homebuilders and banks have rolled over. Oil at 65 will put pump prices at new records and finally influence consumer behavior. Gas prices always came back down in the past. New records will put that into question in consumer minds. 1253 is strong resistance and I thought we would challenge it at least once. We still might if something caused a selloff in oil, but stop waiting for inventories to do it. In commodities, price leads inventories. To me, oil looks like its entering the final phase of a blowoff top. I would not venture a guess to where that top could be. Bull markets in commodities accelerate near the end of their movcs. Remember gold going to 850? It was moving $50 a day toward the end, or beans in the teens or nasdaq to 5000, you get the idea. Pick a top? Not me. It's just doing its job. With so much demand, price has to ration supply. The danger of course is that we can't seem to do anything about it and the price might break the economy. I know the Fed will ease, but this time it may finally be pushing on a string.
The market acts like it definitely wants to go up. Any slight pullback in oil is an excuse for a rally. Rising bond yeilds however, seem to stop it in its tracks. Something to be on the alert for is any sign of economic weakness might cause a bond rally which ironically might ignite stocks. Short banks, homebuilders, and retail and stay long the energy group.
Even though the interest rate spread continues to widen in the dollar's favor, it continues to weaken. Stronger economic fundamentals in Euroland and Japan are overriding the rate advantage. Gold and gold shares have gone along for the ride. Higher oil and commodities in general are also pulling gold along. If bond yeilds continue to rise, can this continue? Opinions welcome.
Stocks did creep higher as I suggested in my last post, until they ran into weaker retail sales and higher oil. Bonds continue to be short and although the dollar did not get to 118 euro, I was correct in thinking it was about time to short the dollar.
Oil stocks have been the undisputed leaders, followed by homebuilders and retailers. So it should be. We are after all a consumption based economy. Financial stocks are the biggest sector of the S&P, and they have lagged badly. The higher bond yields and oil prices hurt 3 out of the four sectors very badly. Homebuilders look like they have finally topped out helped along by prodigious selling by insiders of course. The flat yield curve is hurting net interest margins and so the banks stocks got hit. The BKX looks like its broken down. Retailer's also were sold, starting with Target, the subject of a bearish Barrons article. The group sports pretty high PEs for such large companies in such a mundane businesses. Over the long run their sales growth can't run ahead of GDP. Just ask WMT. That leaves the energy stocks, and at least today they can't lift the entire market by themselves.
A few recent indicators have also become troubling. Sentiment, as reflected in the number of weeks that bulls have outnumbered bears at 145 is approaching its record of 152 weeks. Mutual Fund cash levels are at historic lows. Real Estate as a percentage of GDP is at a historic high. Insider selling is very high. The breadth divergence between big and small stocks is very wide. The current acct deficit at 6 1/2% of GDP is in no mans land. None of these are very good timing indicators, but together they do paint a picture of caution. We can't all get out the door at the same time.
The market continues firm since my last post. The S&P is up about 9 points to 1233. Bonds and the dollar have not changed one iota. Let's be honest. We are in the summer doldrums. We have had a China revaluation, lots and lots of earnings, Greenspan testimony, and the usual economic stats, and nothing is moving the markets very much. Volatility is so low its hard to sit through a whole day of trading. What are you e-mini traders doing?
It would not surprise me to see stocks continue to creep higher. I'll try another short at 1250 on the S&P. I'll stay short bonds untill I see economic weakness and I will start thinking about a short dollar position if the euro falls to the 117-118 area.
There is a lot of talk lately that oil has reached a short to intermediate top. This will be important if true. Energy stocks have been the leaders that have pulled the market higher. Financial stocks have lagged. Some of the big banks in their earning reports had lower net intest income because of the flat yield curve. The other leaders in the market and the economy , are the homebuilders and retail stocks. They have had great runs and are near their highs, but look tired. If oil comes down, what's going to pull the market higher.
The S&P is up 28 pts from my last post, from 1196 to 1224. The prime mover in my mind being that so far there has been no visible impact on the economy or earnings from either higher oil or higher short term interest rates. Those of us, and we are legion, who thought the consumer was overleveraged, underpaid, undersaved, and would be hurt by low income growth in wages and salaries, and squeezed by higher oil prices and rates, Not!!!!! Neither higher gas prices or heating bills or air condidioning for that matter, which have increased substantially, look no further than the huge increase from utilitiies in the latest industrial output report, have made much of a difference lately, Look no further than the latest strong retail sales report. Think pent up demand has been spent, think sales have been pulled forward. No evidence in sight yet. Look at the appettite for SUV's during GM's latest sales incentive.
The consumer cuts back his standard of living very reluctantly, even during recessions, studies have shown. The housing bubble has let homeowners extract ever increasing amounts of cash out of their equity according to BCA Research in their July 7 report. As postulated in an earlier post, and end to this process could likely be the trigger for the inevitable economic slowdown. As has been shown in Holland and the U.K. even just a flattenting in home prices can be quickly felt in retail spending. Even super bears are starting to throw in the towel or waffle on their timing, like Michael Metz last week. There are a few signs, like the dollar stores are underperforming the retail index, and they of course cater to the lowest strata of shoppers. Fewer new home buyers can qualify for loans due to higher home prices in hot markets. Signs like these will have to become more wide spread for the market to take heed. We will be patient in the meantime.
Friday and today the market seems to have stalled. The leaders, oil stocks an homebuilders have sucumbed to profit taking. Oil inventories seem comfortable and the hurricane fears have receded, so taking some chips off the table seems reasonable. All this talk of the Fed not stopping soon provides a similar excuse in the homebuilders after some big moves. Today Citi also dissapointed, in the biggest sector of the market. Last week Fifth Third as well. The Contrarian Investor.com had a great report foreshaowding these results.
I'm still short bonds. Nothing has happened to change my mind, that until we see some economic weakness the curve will have trouble flattening further, and the Fed will push rates higher. The dollar will be supported as long as higher rates are expected.
The S&P is down about 15pts from my last post, from 1211 to 1196. What has happened is that oil reached the tipping point of $60. Oil had been advancing smartly the weeks before by about 8% without any adverse impact on stocks. But a $60 oil price was enough to cause a couple of triple digit down days for the Dow. The market then got back 50% of its losses, recovering to 1204 when oil broke back below $57. There was also some hope that the Fed might signal an end to their rate increases. Those hopes were dashed yesterday and the market sold off. Economic wise, we get a nice bounce in the purchasing managers index and the consumer sentiment numbers are supportive. The economic news has not been a big mover lately.
It is all about the Fed, oil and soon earnings. The euro fell below 1.20 today, not good for multinational earnings. The Fed is not done, also not good for the market. There is no sign of economic weakness in housing and autos. If you squint you might see the consumer slowing down a little. To me it all adds up to oil and earnings being the swing factors over the next couple of weeks. I'm skeptical of this fall in oil being little more than profit taking after hitting a big round number as the oil stocks gave up very little. On profits I fear higher commodity cost and a stronger dollar hurting margins. I'm shorting the market on rallies with a stop at 1206.
I'm short term bearish on the bonds now. I think the curve will have trouble flattening further until we see some sign of economic weakness, so I've gone short for a trade. Prices have approached the old highs and they are technically overbought.
The euro looks like it can fall to 117-118. Like Bill Gross I believe economic weakness is enevitable down the road and that is what I think will turn the buck lower again. For now the interest rate theme provides the lift.
Well here we sit, right about where we stared the year. Considering all the potential negatives, not too bad a showing. Higher interest rates are almost a positive for the market as it must mean the Fed's almost done. The same can't be said for the higher dollar or oil, at least not in my mind. The higher dollar is going to negatively impact some second quarter corporate profit reports. Oil will do the same as well as hurt consumer spending this summer.
I've written about this before, but I think it bears repeating. This market reminds me a lot of 86-87. The market just kept shrugging off all the negatives and floating higher until itdidn't.
We had trade frictions with the European and Japanese, record current a/c deficits, a budget deficit 4% of GDP, commodity prices moving higher as well as the CPI, gold moving up from 360 to 420 and yet GDP growth of 3 1/2% with Fed Funds moving higher.
Then the trigger was Secretary baker threating the Europeans over a weekend with letting the dollar fall to correct our current a/c deficit if they didn't lower their rates and reflate so they would buy more of our exports. The U.S. couldn't be the only economic engine of growth, it was argued.
What will be the trigger this time? It could be an oil spike, a trade war with China , or the housing bubble bursting, or something completely out of left field. I lean toward the housing market being the culprit. Consider the following scenario. Housing prices continue to escalate. As a consequence fewer and fewer people can qualify for mortgages as their incomes have not kept pace. Sales slow down. Prices fall ending the wealth effect on consumer spending.
You can write your own ending.
We are up 10 S&P points from my last post 5/26, all of it coming today. The last surge up came from China bashing and the beneficial effects a revaluation would have. Today's rally comes from Greenspan's comments, that bond yields will stay low and a flat yield curve may not mean economic weakness the way it has in the past. Recent evicdence of economic weakness is being taken in stride, as the pause that refreshes. It is ascribed to an inventory correction largely attributable to the auto sector, that is now being worked off with better things to come in the second half. Friday's weak employment report is a distant memory. If final demand continues to hold up, then all the above is true. Long rates might get low enough to inspire another round of mortgage refinancings which would bolster the demand side. It's a light week for data and so a good week for a market rally. Although the market ignored it, Greenspan did say the bond market could be signaling economic weakness. So when the data flow resumes the sledding will get tougher if it follows the lead of the payroll numbers.
At the time of my last post, May 19, the S&P was at 1190, about where it closed last night. As I write we've popped back up to 1197, not to far from 1211 where we started the year. So overall the sideways action continues, making life hard for traders and investors alike. The goldilocks environment of 3% growth, low interest rates and low inflation provides support while the things we worry about-- trade deficit, budget deficit, high oil prices, flattening yield curve, declining leading indicators, real estate bubbles, etc. hamper the upside. The day to day statistics, earnings and news moves things up a little or down for a few days, but we always seem to revert to the mean. Eventually I believe the things we worry about will tip the scales lower beacuse some of them are unsustainable. The timing however is and has been quite uncertain. The resillency of the U.S. economy is amazing.
Next week looks to be moreof the same, slightly weaker economic stats, but nothing earth shattering it appears. However you never know what will tip the scales. Be wary of weak economic stats because one could break the camels back. The push up today got its impetus from Treasury Secretary Snow"s testimony putting more heat on the China to revalue. While this is certainly not good for mainstreet, having to pay higher prices for imported goods, it will have an immediate positive effect on corpoate profits. Good especially for those multinationals with a high percentage of their revenues coming form asia. In other currency matters, it will be interesting to see how much of an effect the French vote has on the euro, if they vote no on the EU constitution.
As I said in my last post, as long as there were no hedge fund disasters, the market could continue to gather strength. That was the first impetus, as nothing untoward happened over the weekend. Then came the Treasury report on China, putting them on notice to loosen their currency peg or else. Finally the core CPI at 0% was the frosting on the cake. Today so far, it looks like the better than expceted jobless claims are cancelling out the worse than expected Philly Fed index, which has been quite erratic lately. So the S&P sits at resistance near 1190. The bonds sit near 4% resistance in yield and gold is around $420 support. Also it is not uncommon for stocks to hit their high around options expiration. The point being, that this would be a natural area for consolidation or reveral of current trends. No shocking news seems to be on tap for next week, which also fits the scenario. With this backdrop beware of false breakouts. 
When I left on vacation 4/21 the S&P was at 1159 same as when I returned on May 3. As I start to write this blog it is trading at 1161. I love the quote by Martin Goldberg today on Financial Sense.com "The S&P500 touched 1155 on January 27th, 2004, over 15 mos ago and as of Wednesday night sits at about that same level. In that time, there has been so much analysis, so little movement and so much money floating about looking for a speculative gain." Isn't that the truth. In contrast however, on 4/21 oil was 54.20 vs 48.40 as I write. The dollar was 130,48 against the euro vs 126.32 now. 10yr notes were 4.22 vs 4.13 now. Gold was 434 vs 420 today. So, with all this activity, why haven't equity prices had a net change? A few weeks ago we were fretting over an economic soft patch, that now with the latest releases of retail sales, payrolls, and auto sales common wisdom says is over. GDP will be revised higher. With oil down $6 and 10yr note yields at 7 month lows, earnings pretty good, you would think equities would be higher than three weeks ago. My explanation for why they are not is simply, liquidity is contracting and the ripple effects of the GM and Ford downgrade to junk on the psychology and risk appetite of market participants is casting a pall. It scares the hell out of everybody and they pull back. First Fannie and Freddie, and AIG and now GM and Ford. Credit problems with interest rates this low. What if they move higher? Who else then gets caught. Credit spreads are widening as everyone waits to see if another shoe falls. Time will heal this wound. Everyday no hedge fund fails the market can gather strength.
I do have my reservations over the economic data maybe not being as strong as it appears. If you average March and April together it doesn't look as much has changed. Consumer confidence droped again and the purchaseing managers report was weak. Europe and Japan also continue weak.
To me, today's stock market strength stems from three factors. First, auto sales we pretty good in May, a 17 1/2 million annual rate. Fears that the economy is falling out of bed are not supported by this strong demand. Take heart, those in the soft patch camp. Secondly, the Fed is done for two months regardless of what they do at the next meeting. We have a respite. Third, oil inventories continue to rise. Crude finished up on the day, but with these numbers, we are not going to $60 anytime soon. So, if the economy can grow at 3% with oil at $50, and the Fed hasn't hurt the economy yet with talk that they are close to done, and profits are good. What's not to like. Thats the bull case that took the lead today.
Back from vacation refreshed and eager to jump back in. I left on the 21st of April, and the S&P clsoed at 1159.95 that day. As I write at 10:30 am the S&P is trading at 1159.51. On a net basis I didn"t miss much. You did have some big up and down days. The market hit its high, 1229 on the S&P on Mar 7. Crude oil was around 54, on its way to 57.46 closing high on 3/21 and the 10yr note yielded 4.3 on it's way to 4.6.from 4 in early Feb. So the market peaked about three weeks before oil and interest rates did. It was the combination of higher oil and interest rates that turned the market down, similar to past spikes in oil prices, 3/00 and 8/90. As they continued higher the market went lower. Even after they peaked and went lower the market declined. Here we are today and oil is close to $50 and notes around 4.20% and the market still struggles. The question is has oil done enough damage to cause a significant economic and profit slowdown. Gas is still $2.25 a gallon, so are the effects still working themselves into the economy. Secondly, to what levels must interest rates and oil fall to become positive catalysts to the market. In both the 1990 and 2000 spikes, oil came down to $20. One would think that long rates at these levels would be very supportive to the market, real estate and housing. But we are at a point where, if the 10yr breaks 4% in yield it could be interpeted very negatively.
The dollar continues to get support from the economic weakness in Europe and Japan and from rate hikes here in the U.S. not to mention the uncertainty around the EU constitution. Our problems however are large and structural. They won"t go away soon. The budget deficit, trade deficit, and overleveraged consumer and low savings rate to name a few. One could take comfort that we are at a higher absolute level of economic growth than Europe or Japan, but that might just mean we have farther to fall. In the 70's what made the dollar so weak was the European central banks had greater credibility as inflation fighters than the Fed. They only have one mandate-fight inflation and maintain the integrity of the currency. Economic growth was the politicians problem. Germany had been through hyper inflation making their currency worthless. The Fed on the other hand is always torn between two masters and your always guessing which one they will serve. If this slowdown continues will they continue their measured tightening? If not, keep your eye on the dollar then.
The positive effects of lower oil prices on stocks was agian over ridden by economic weakness. This was very similar to what happened a few days ago when we got lower oil prices but a large drop in the transport index, based on economic weakness drove the market lower. Yesterday the culprit was weak retail sales. Just about everyone has been talking about if and when the overindebted consumer will crack for over a year now, so its a big deal. Ex auto and gas the number was -.1%,. The last time it was negative Greenspan was talking about a soft patch. Obviously this can have important ramifications for the dollar and interest rates.
I have a hunch that the pattern we will see now, is weakness on days of reports reinforcing the economic weakness theme and recoveries thereafter. We have very supportive oil prices and long term interest rates to provide some rally days.
The dollar is stronger on an IMF report reinforcing the theme of stronger U.S. growth and weaker growth in Europe and Japan. This is old news of course. The euro should find support around the February lows of 127.40. It should start to firm if more sign of U.S. economic weakeness emerge.
The headlines say "stocks trade higher on FOMC minutes". It isn"t that simple. Today was a very complex day. Readers of this blog know I have been using a very simple but effective index lately. As an example, if oil is $55 and the 10yr yield is 4.5% the index value is 10. Stocks have been weak when the index is over 10 and stronger when the index is under 10. A few days ago when oil broke $55 on the downside, I expected stocks to firm. They didn't because on that same day the transports crashed on USFC's earnings warning. The trucking company's weakness spread to the other transports and then to the market in general. The warning did not blame higher oil, but rather weakness in the auto sector and a slowdown in business in the northeast U.S. That is why the weakness spread to the general market. It implied a weakning economy and the cyclicals got hit. Oil continued to come down yesterday and more today. When the FOMC minutes came out and caused a modest rally in bonds that was the straw that broke the camels back, as higher interest rates were not going to offset the benefit of a $5 drop in oil. The Dow staged a 140 pt turnaround. With the index now at 9.58 there should be good support for stocks.
To many the, action in the dollar was confounding as well. It fell as soon as the record U.S. trade figures were released but then did a 180 and rallied almost a 100 pips at the close.
I won't argue if a record deficit was expected or not, but we know they are going to be large every month, particularly if oil prices are high that month. I believe what is keeping dollar sellers sidelined is the G7 meeting in Washington this weekend. The G7 is going to pressure China once again to do something about their currency. Notice, I said G7 and not the U.S. If and when they finally act it will take a lot of pressure off the euro. Any action or statement hinting they are leaning that way will be enough to send the buck flying.